Skip to content
Hardev puri, Delhi, 110093

Business hours

Delhi GST & Tax Experts

Monday
9:30am-6pm
Tuesday
9:30am-6pm
Wednesday
9:30am-6pm
Thursday
9:30am-6pm
Friday
9:30am-6pm
Saturday
9am-6pm
Sunday
9am-5pm

You can anytime during the day with your query.

8076868203

Latest Posts & Updates

Fresh stories, announcements and offers about Tax Advisor, straight from our business.

📢 ITAT Chennai Deletes Entire ₹5.73 Cr 143(1) Demand

143(1) Show-Cause Issued: ITAT Quashes ₹5.73 Cr Demand for TDS Mismatch The ITAT has held that a 143(1)(a) adjustment cannot be made without issuing a mandatory show-cause/intimation, especially in cases of TDS–income mismatch. A prior 139(9) defect notice cannot substitute the statutory requirement of a 143(1) intimation. Since no notice was issued before denying TDS credit of ₹5.05 crore, the Tribunal ruled the adjustment invalid and ordered complete deletion of the ₹5.73 crore demand. Key Takeaway: Due process under Section 143(1) is mandatory—no adjustment without prior intimation.

📢 ITAT Chennai Deletes Entire ₹5.73 Cr 143(1) Demand post imageRead full post

🔍 Major GST Updates in November 2025

1. Time-bar on Old GST Returns o From the November 2025 tax period, GST returns that are more than 3 years old (i.e., due-date was 3+ years back) will no longer be allowed for filing. o Specifically: GSTR-1 / GSTR-3B for October 2022 and GSTR-9 for FY 2020-21 become time-barred. 2. Faster Refunds for Inverted Duty Structure (IDS) o From November 1, 2025, taxpayers who have inverted duty structure (i.e., their input GST > output GST) will be eligible for a 90% provisional refund on unutilised input tax credit (ITC). o The remaining 10% will go through verification. o This is expected to improve cash flow for many MSMEs. 3. Simplified GST Registration for Low-Risk Businesses o From Nov 1, 2025, a simplified registration scheme will kick in. o Businesses whose monthly B2B output tax liability is ≤ ₹ 2.5 lakh can opt for this. o Their registration applications will be auto-approved within 3 working days, without manual checks / site visits. o There is opt-in / opt-out flexibility. 4. Strict Correction Window for FY 2024-25 o You can amend sales/purchase/credit details for FY 2024-25 only up to the October 2025 return. o According to reports, there won’t be extensions or grace periods beyond that. 5. Credit Notes Pending Feature o A feature is being tested on the GST portal: credit notes can remain “pending” for up to 1 month before final submission. o This helps suppliers reduce errors and improves cross-verification.

Read full post

🚀 Automatic GST Registration in Just few minute ! | GST 2.0 Launching November 2025

Great news for entrepreneurs and small businesses! Starting November 1, 2025, the government will roll out GST 2.0 — a simplified registration system designed to automatically approve GST applications within 3 working days. ✅ 💡 Key Highlights: Auto-approval within 3 working days is now available in two cases: Applicants identified as low-risk by the system, and Applicants who self-assess that their monthly output tax on B2B supplies (inclusive of CGST, SGST/UTGST, and IGST) does not exceed ₹2.5 lakh. The scheme is voluntary — applicants can opt in to the simplified lane or continue under the regular registration process. The existing legal framework under Rule 8 and Rule 9 of the CGST Rules, 2017 remains in force. The simplified GST 2.0 process overlays but does not replace these rules. The GST Council estimates that 95–96% of new applicants will qualify under this simplified lane. ⚖️ Statutory Context: Rule 8: Application for registration, TRN generation, Aadhaar authentication, and biometric protocols. Rule 9: Verification and approval timelines (7 or 30 days) and deemed approval provisions. 📈 With GST 2.0, starting and scaling your business just became faster, easier, and more transparent!

🚀 Automatic GST Registration in Just few minute ! | GST 2.0 Launching November 2025 post imageRead full post

🚀 Automatic GST Registration in Just 3 Days! | GST 2.0 Launching from November 2025

Great news for entrepreneurs and small businesses! Starting November 1, 2025, the government will roll out GST 2.0, a simplified system that allows automatic GST registration approval within 3 working days. ✅ 💡 Key Highlights: Data-driven, transparent registration system Automatic approval for 96% of applicants Applies to low-risk businesses & those with < ₹2.5L monthly tax liability Faster refunds & simplified return filing Rationalised GST rate slabs Finance Minister Nirmala Sitharaman announced that GST 2.0 will make the tax system more efficient, equitable & growth-oriented, focusing on ease of doing business and respectful taxpayer service. 💬 “The system must work by design, not by discretion.” — FM Nirmala Sitharaman 📍 Businesses can look forward to a more seamless, transparent, and accountable GST experience.

🚀 Automatic GST Registration in Just 3 Days! | GST 2.0 Launching from November 2025 post imageRead full post

Can GST Registration be Cancelled for Filing NIL Returns or Non-Commencement of Business for 6 Mo…

Can GST Registration be Cancelled for Filing NIL Returns or Non-Commencement of Business for 6 Months? Let’s understand the legal provision + case laws 1. Legal Provision — Rule 21(a) of CGST Rules, 2017: - Registration is liable to be cancelled if the registered person does not conduct any business from the declared place of business or has not commenced business within six months from the date of registration. So, if you obtain GSTIN but continuously file NIL returns (no turnover, no activity) for 6 months — it may be treated as non-commencement of business and invite cancellation. 2. Combined Reading of Rule 21(a) & 21(b): - Rule 21(a): Non-commencement of business within 6 months Rule 21(b): Failure to furnish returns for 6 continuous months Filing NIL returns for 6 months can be seen as both —Non-commencement of business, and Failure to carry on genuine business activity. 3. Departmental Action If either condition exists, officer may: Issue Show Cause Notice (REG-17) Allow 7 working days to reply in REG-18 Pass Cancellation Order (REG-19) During the process, your GSTIN may be suspended — meaning no invoicing or ITC allowed. 4. Key Case Laws (a) Suguna Cutpiece Center v. Appellate Deputy Commissioner (ST)(Madras HC, 2022 – 2022-TIOL-508-HC-MAD-GST) Held : - that cancellation solely for non-filing of returns or NIL activity, without proper enquiry or opportunity, is invalid. (b) ARS Steel & Alloy International Pvt. Ltd. v. STO(Madras HC, 2021 – 2021-VIL-52

Read full post

दीप जलते-जगमगाते रहें, हम आपको और आप हमें याद आते रहें, जब तक जिंदगी है, ये दुआ है हमारी कि, आप ह…

दीप जलते-जगमगाते रहें, हम आपको और आप हमें याद आते रहें, जब तक जिंदगी है, ये दुआ है हमारी कि, आप हमेशा मुस्कुराते रहें। शुभ दीपावली! मां लक्ष्मी का हाथ हो, सरस्वती का साथ हो, गणेश जी का निवास हो, और मां दुर्गा के आशीर्वाद से, आपके जीवन में प्रकाश ही प्रकाश हो। शुभ दीपावली। 🙏🙏🙏🙏

दीप जलते-जगमगाते रहें, हम आपको और आप हमें याद आते रहें, जब तक जिंदगी है, ये दुआ है हमारी कि, आप ह… post imageRead full post

Big Tax Relief in GST for Sept return 2025

Key tax reliefs Extended filing deadline: The due date for filing the GSTR-3B return for September 2025 has been extended to October 25, 2025, for both regular and quarterly taxpayers. Simplified GST structure: The previous four GST slabs (5%, 12%, 18%, 28%) have been replaced by a simpler two-slab system of 5% and 18%. Rate cuts on numerous goods: Daily essentials: Items like packaged milk, paneer, butter, ghee, dry fruits, and chocolates have seen their GST reduced from 12% or 18% to 5%. Electronics: TVs (up to 32"), air conditioners, and washing machines have had their GST lowered from 28% to 18%. Vehicles: Small cars and motorcycles with engines up to 350cc have seen their GST cut from 28% to 18%. Agriculture: Tractors and various agricultural machinery have had their GST reduced from 12% to 5%. Healthcare: GST on general medicines has been reduced to 5%, and many life-saving drugs and diagnostic equipment are now at 0% or 5%. Construction: Cement rates have been reduced from 28% to 18%.

Big Tax Relief in GST for Sept return 2025 post imageRead full post

Attention : Important Advisory on IMS

It has come to notice that some posts are circulating incorrect information regarding changes in GST return filing from October 1, 2025. We would like to clarify the following: I. No Change in Auto-Population of ITC: Input Tax Credit (ITC) will continue to auto-populate from GSTR-2B to GSTR-3B without any manual intervention. The mechanism of auto-population remains unchanged due to the implementation of the Invoice Management System (IMS). II. GSTR-2B Generation GSTR-2B will continue to be generated automatically on the 14th of every month, without any manual intervention by taxpayers or based on the actions taken by the taxpayers. Taxpayers can take actions in IMS even after generation of GSTR-2B till filing of GSTR-3B and can regenerate GSTR-2B accordingly, if required. III. Credit Note Handling (Effective October 2025 period onward) Recipient taxpayers will have the option to keep a Credit Note or related document pending for a specified period. On acceptance of Credit Note or related document, the recipient will also have the flexibility to reduce ITC only to the extent of its availment by adjusting the reversal amount manually.

Read full post

Section 8 of the Central Goods and Services Tax (CGST) Act, 2017, is the key provision for classi…

Section 8 of the Central Goods and Services Tax (CGST) Act, 2017, is the key provision for classifying and taxing transactions that involve a bundle of two or more distinct goods or services supplied together for a single price. The law differentiates between two types of bundles: Composite Supply and Mixed Supply, and assigns a specific tax treatment to each. A Composite Supply is defined where two or more supplies are naturally bundled and provided in conjunction with each other in the ordinary course of business, with one supply clearly being the principal supply. In this case, as per Section 8(a), the entire transaction is treated as a supply of the principal item, and the GST rate applicable to that principal supply will be charged on the total value of the bundle. For example, a flight ticket that includes a meal is a Composite Supply, and the entire amount is taxed at the rate of the principal service, which is air transport. Conversely, a Mixed Supply occurs when the bundle of items is not naturally bundled and could easily be sold separately. If the bundle fails the 'naturally bundled' test, Section 8(b) mandates that the entire supply must be treated as the supply of that specific item within the bundle which attracts the highest rate of tax. This rule is a deterrent against tax avoidance, as it ensures that high-tax items cannot be bundled with low-tax items to lower the overall tax liability. A common example is a festive gift hamper containing unrelated items lik

Section 8 of the Central Goods and Services Tax (CGST) Act, 2017, is the key provision for classi… post imageRead full post

Business Owners, Entrepreneurs & Startups – Listen Up!

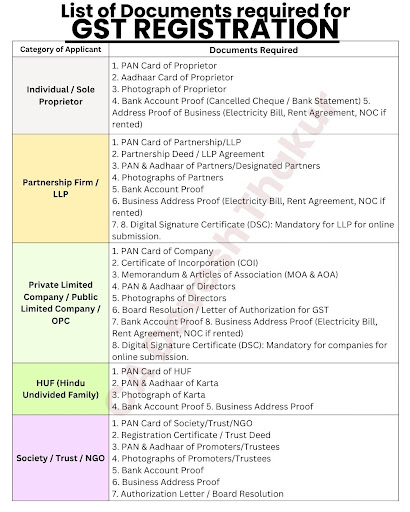
Thinking of starting your business but stuck at GST Registration? Don’t let confusion stop your growth! Here’s the **ULTIMATE GST Registration Checklist**– made SIMPLE for you. No jargon, no stress… just a clear list of documents you need to get your GST done Whether you’re a **Proprietor, Partnership, Pvt Ltd, HUF or NGO**, this guide covers it ALL. Save this post, share it with your business circle & never miss a document again!

Business Owners, Entrepreneurs & Startups – Listen Up! post imageRead full post

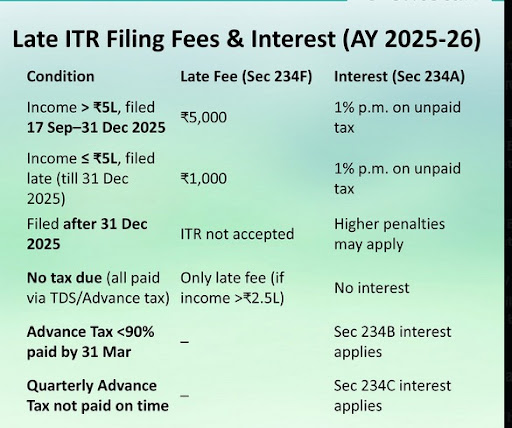
✅ Key Deadlines for FY 2024–25 / AY 2025–26

Original due date (Non-audit cases): September 16, 2025 Last date to file belated ITR: December 31, 2025 ⚠️ Consequences of Filing ITR After the Deadline Late Filing Fee (Section 234F): Income ≤ ₹5 lakh → ₹1,000 Income > ₹5 lakh → ₹5,000 Interest Charges (Sections 234A, 234B, 234C): 234A → Interest on tax unpaid as of the due date. 234B → If advance tax paid <90% of total tax liability. 234C → If advance tax not paid in correct installments. Loss of Carry Forward Rights: Business loss, capital loss, and other losses (except house property loss and unabsorbed depreciation) cannot be carried forward if return is filed after due date. Delayed Refunds: Any expected tax refunds may take longer. Increased Scrutiny: Late filing may lead to greater likelihood of notices or assessment from the Income Tax Department. 🎯 What You Should Do Now If you’re required to file ITR and missed the due date: File a belated return immediately, before December 31, 2025. If you’re unsure whether you were required to file, consider: Gross total income before deductions > ₹2.5 lakh (or ₹3L/₹5L for senior citizens)? Have foreign income/assets? TDS/TCS deducted but no ITR filed? High-value transactions (investments, credit cards, etc.)? 📝 Additional Tip: You can revise a belated ITR (if errors found) only till December 31, 2025, so be careful while filing.

✅ Key Deadlines for FY 2024–25 / AY 2025–26 post imageRead full post