Skip to content
Hardev puri, Delhi, 110093

Business hours

Delhi GST & Tax Experts

Monday
9:30am-6pm
Tuesday
9:30am-6pm
Wednesday
9:30am-6pm
Thursday
9:30am-6pm
Friday
9:30am-6pm
Saturday
9am-6pm
Sunday
9am-5pm

You can anytime during the day with your query.

8076868203

Latest Posts & Updates

Fresh stories, announcements and offers about Tax Advisor, straight from our business.

🔔 Key PAN Transaction Changes

Effective from April 1, 2026 The draft Income Tax rules propose higher limits for mandatory PAN quoting in several transactions. Here’s what you should know: 💰 Cash Deposits & Withdrawals PAN required if aggregate cash transactions exceed ₹10 lakh in a financial year. (Current rule: ₹50,000 in a single day) 🏠 Property Transactions Reporting threshold proposed to increase from ₹10 lakh to ₹20 lakh for sale/purchase of immovable property. 🚗 Motor Vehicles PAN required for vehicle purchases exceeding ₹5 lakh. ✔ Now includes high-value two-wheelers ✔ Tractors remain excluded 🍽 Hotel & Restaurant Payments PAN mandatory if cash payment exceeds ₹1 lakh. (Current limit: ₹50,000) 🛡 Insurance Policies PAN will be mandatory to start any account-based relationship with an insurance company, irrespective of premium amount. 📌 These changes aim to improve transparency while easing compliance through higher thresholds. 📞 For PAN compliance, Income Tax advisory or documentation support: Delhi GST & Tax Experts

🔔 Key PAN Transaction Changes post imageRead full post

🔔 Big Change in GSTR-3B from Jan/Feb 2026 | New GST ITC Rules 2026

Big relief for taxpayers! The GST Portal is introducing a system-level change in ITC utilisation from January 2026 tax period onwards, impacting GSTR-3B filings (Feb 2026 onwards). ❌ Earlier Problem (Old ITC Set-off Rule) Under the old rules: • IGST ITC had to be used first (IGST → CGST → SGST) • CGST & SGST ITC could not be cross-utilised • Taxpayers were forced to pay cash, even when ITC was available in another head This caused working capital blockage and practical hardship. ✅ What’s the Big Change from Jan 2026? 🔹 New logic in Table 6.1 of GSTR-3B 🔹 Once IGST ITC is fully exhausted, taxpayers can now: ➡ Use CGST & SGST ITC in any sequence ➡ Settle IGST liability without cash payment ✔ System-enabled flexibility on GST Portal ✔ No change in law, but major portal relief ⭐ Key Benefits • Avoids unnecessary cash outflow • Better ITC utilisation & liquidity • Prevents ITC accumulation • Simplifies compliance & reduces errors ⚠️ Important Points • CGST ↔ SGST cross-use still not allowed • Allowed only for IGST liability • Applicable prospectively from Jan 2026 • Review ITC balances carefully before filing GSTR-3B 📞 Need help with GSTR-3B, ITC planning, or GST compliance? Delhi GST & Tax Experts We help you save cash & stay compliant.

🔔 Big Change in GSTR-3B from Jan/Feb 2026 | New GST ITC Rules 2026 post imageRead full post

🔔 UPI और GST Linking – सच्चाई और नए नियम (2025–26)

UPI और GST को लेकर सोशल मीडिया पर कई भ्रामक खबरें चल रही हैं। आइए जानते हैं वास्तविक नियम और वर्तमान स्थिति: ✅ 1️⃣ UPI लेनदेन पर कोई GST नहीं भारत सरकार ने स्पष्ट किया है कि UPI पेमेंट पर कोई GST नहीं लगता, चाहे राशि ₹2,000 से अधिक ही क्यों न हो। वित्त मंत्रालय ने GST लगने की खबरों को गलत और भ्रामक बताया है। 🏪 2️⃣ व्यापारियों (Merchants) के लिए नियम 🔹 QR Code अनिवार्य: ₹50 करोड़ या उससे अधिक टर्नओवर वाले व्यापारियों के लिए UPI-आधारित QR Code लगाना अनिवार्य है। 🔹 GST भुगतान में UPI: अब व्यापारी GST Portal → Create Challan के जरिए UPI से GST भुगतान कर सकते हैं। 🏦 3️⃣ बैंक और NPCI का अपडेट 🔹 GSTIN / ISD Linking: NPCI ने नवंबर 2025 में बैंकों को अपने सिस्टम में GSTIN / ISD विवरण अपडेट करने का निर्देश दिया है, ताकि GST रिपोर्टिंग सही हो। 🔹 GST नोटिस: GST विभाग अब UPI ट्रांजैक्शन डेटा के आधार पर यह जांच कर रहा है कि कहीं टर्नओवर छुपाया तो नहीं गया। 📅 4️⃣ 2026 में क्या बदल सकता है? जनवरी 2026 से: ✔ डिजिटल पेमेंट पर अधिक पारदर्शी रिपोर्टिंग ✔ GST-QR सिस्टम में नए बदलाव ✔ छोटे व्यापारियों के लिए स्पष्ट GST अनुपालन नियम ⭐ मुख्य बात 👉 ग्राहक (Customer): UPI पेमेंट पर कोई अतिरिक्त GST नहीं 👉 व्यापारी (Merchant): UPI सहित सभी डिजिटल लेनदेन GST टर्नओवर में शामिल होते हैं 📞 UPI–GST Linking, GST Payment या Notice से जुड़ी सहायता के लिए संपर्क करें: Delhi GST & Tax Experts हम आपके GST अनुपालन को सरल बनाते हैं।

🔔 UPI और GST Linking – सच्चाई और नए नियम (2025–26) post imageRead full post

📊 1. GST Rate Changes (Effective Feb 1, 2026)

• The Government has restructured GST on tobacco & “sin” goods — the old 28 % slab removed. New GST rates: o 18 % or 40 % GST on tobacco products & pan masala, based on classification. o **GST compensation cess on tobacco products reduced to nil. o New MRP-based GST valuation for certain items introduced. • Alongside this, a reinstated central excise duty regime applies to specific tobacco products with compliance tied to machine/production rules. 👉 These changes come into effect from 1 February 2026. 🧾 2. Major GST Structural Reform — GST 2.0 Though implemented in September 2025, the effects are currently rolling out and relevant in January 2026: • The GST slab system was simplified — major slabs consolidated mainly into: o 5 % and 18 % o A 40 % “sin/luxury” slab for selected goods (e.g., luxury and harmful products). • Essentials (e.g., basic food items) in many cases moved to lower slabs or zero GST. • Items like consumer durables, small vehicles saw rate reductions. (This restructuring — often called “GST 2.0” — continues to affect pricing, compliance and revenue distribution across industries.) 📈 3. GST Revenue & Collections • GST collections for December 2025 were robust — crossing around ₹1.74 lakh crore, roughly 6 % higher year-on-year. • For the entire April-December FY 2025-26 period, collections also showed growth compared with the p

📊 1. GST Rate Changes (Effective Feb 1, 2026) post imageRead full post

✅ GSTR-9 Annual Return – Due Date, Applicability & Key Rules (FY 2024-25)

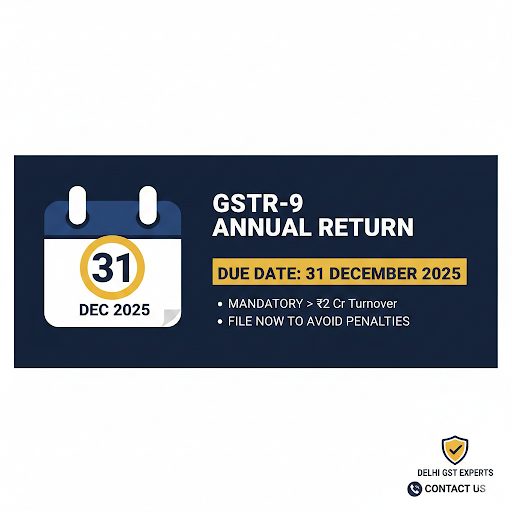
GSTR-9 is the annual GST return that consolidates data from GSTR-1, GSTR-2B and GSTR-3B, covering sales, purchases, ITC and taxes for the full financial year. 📅 Due Date: 31 December 2025 🔍 Who is Required to File GSTR-9? ✔ Mandatory for taxpayers with aggregate turnover above ₹2 crore ✔ Applicable to Regular GST taxpayers (GSTR-1 & 3B filers) ❌ Not applicable to: • Composition taxpayers • Casual taxable persons • Input Service Distributors (ISD) • Non-resident taxable persons • TDS/TCS deductors under GST 🚨 Important Updates for FY 2024-25 🔹 Turnover up to ₹2 crore → Exempt from filing GSTR-9 🔹 GSTR-9C mandatory where turnover exceeds ₹5 crore 🔹 Revised GSTR-9 & 9C formats notified (new ITC tables, IMS-based auto-population) 🔹 Enhanced ITC disclosures & reconciliation requirements 📊 What GSTR-9 Covers • Annual outward & inward supplies • ITC availed, reversed & ineligible • Tax paid vs tax payable reconciliation • HSN-wise summary • Adjustments identified during annual review ⚠ Any short-paid tax or excess ITC must be paid via DRC-03 before filing. 💰 Late Fee for GSTR-9 (Section 47) • ₹200 per day (₹100 CGST + ₹100 SGST) • Maximum cap: 0.25% of turnover per Act • No IGST late fee Late fee continues until the annual return is filed. ✅ Best Practices Before Filing ✔ Complete GSTR-1 & GSTR-3B filings ✔ Reconcile Books vs GSTR-1 vs GSTR-3B vs GSTR-2B ✔ Identify ITC mismatches & reversals earl

✅ GSTR-9 Annual Return – Due Date, Applicability & Key Rules (FY 2024-25) post imageRead full post

❓ Do You Know?

Does ‘Aggregate Turnover’ include CGST, SGST, UTGST, IGST, and Cess for checking the ₹5 Crore applicability limit? ✅ The Correct Answer: NO. As per Section 2(6) of the CGST/SGST Acts, aggregate turnover EXCLUDES the value of: ✔️ Central Tax (CGST) ✔️ State Tax (SGST) ✔️ Union Territory Tax (UTGST) ✔️ Integrated Tax (IGST) ✔️ Compensation Cess Meaning — GST and Compensation Cess paid are NOT counted while determining whether your turnover crosses ₹5 Crore. 🔍 But here’s the important twist: 👉 All other taxes, duties, and cess (except GST) must be INCLUDED while computing the ₹5 Crore threshold. 🎯 Why This Matters? Because the ₹5 Crore limit decides your: ✔️ Annual Return type ✔️ Reconciliation requirements ✔️ GSTR-9C applicability ✔️ Audit-related compliances 📍 By Delhi GST & Tax Experts Follow for more GST, GSTR-9C & Audit insights!

❓ Do You Know? post imageRead full post

🌟 GSTR-9 & 9C Annual Return Update (FY 2024-25)

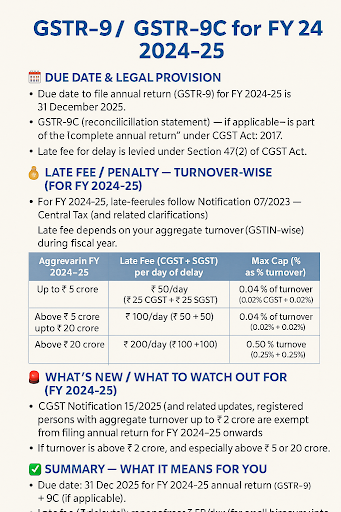
📅 Due Date: 31 December 2025 🔍 Applicable Forms: GSTR-9 (Annual Return) + GSTR-9C (Reconciliation Statement) 🧾 Key Highlights for FY 2024-25 🔹 GSTR-9C is part of the complete annual return under Section 44 (CGST Act). 🔹 Late fee for delay is levied under Section 47(2). 💰 Late Fee Structure (Turnover-Wise) Aggregate Turnover (FY 2024-25) • Up to ₹5 crore → ₹50/day (CGST ₹25 + SGST ₹25) → Max: 0.04% of turnover • ₹5–20 crore → ₹100/day (₹50 + ₹50) → Max: 0.04% of turnover • Above ₹20 crore → ₹200/day (₹100 + ₹100) → Max: 0.50% of turnover ⚠️ Late fee continues until both GSTR-9 and GSTR-9C (if applicable) are filed. 🚨 Important Update (Notification 2025) ✔ Businesses with turnover up to ₹2 crore are exempt from filing GSTR-9/9C for FY 2024-25 onwards. ✅ What You Should Do ✔ File before 31 Dec 2025 to avoid accumulating late fees ✔ Check your turnover category to know the penalty risk ✔ Reconcile data between Tally, GSTR-1, GSTR-2A/2B, and books 📞 Need Expert Help? For GST Annual Return Filing, GSTR-9C Certification, or Turnover Reconciliation, contact Delhi GST & Tax Experts – Your trusted GST compliance partner.

🌟 GSTR-9 & 9C Annual Return Update (FY 2024-25) post imageRead full post

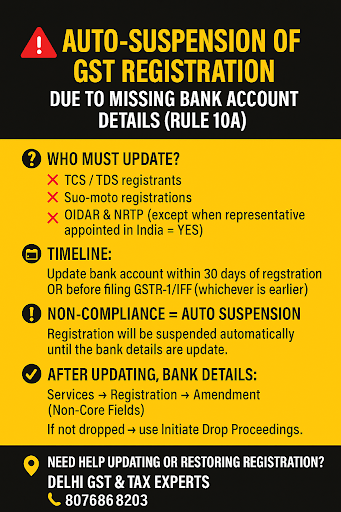
🚨 Auto-Suspension of GST Registration Due to Missing Bank Account Details (Rule 10A) 📌 Who must u…

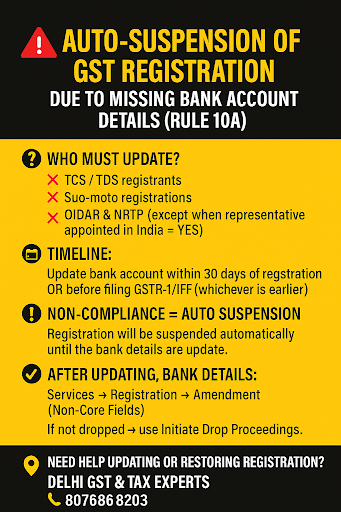
🚨 Auto-Suspension of GST Registration Due to Missing Bank Account Details (Rule 10A) 📌 Who must update? All GST-registered taxpayers except: ❌ TCS / TDS registrants ❌ Suo-moto registrations ❌ OIDAR & NRTP (except when representative appointed in India = YES) 📅 Timeline: Update bank account within 30 days of registration OR before filing GSTR-1/IFF (whichever is earlier) ⚠ Non-compliance = Auto Suspension Registration will be suspended automatically until the bank details are updated. 🛠 How to update bank details: Services → Registration → Amendment (Non-Core Fields) ✔ After updating, the system will automatically drop cancellation proceedings. If not dropped → use Initiate Drop Proceedings. 📍 Need help updating or restoring registration? Delhi GST & Tax Experts

🚨 Auto-Suspension of GST Registration Due to Missing Bank Account Details (Rule 10A) 📌 Who must u… post imageRead full post

🚨 Important GST Update for All Taxpayers!

The GST Portal has rolled out a new automated system that will auto-suspend GST registrations if taxpayers fail to furnish their bank account details within 30 days of registration or before filing GSTR-1/IFF, whichever comes earlier. This update is part of the GST advisory issued on 5 December 2025 under Rule 10A, which makes timely submission of bank details mandatory for all taxpayers except those registered under TCS, TDS, or suo motu registrations. 🔍 What Happens If You Don’t Submit Bank Details? If the required bank information is not furnished within the permitted time, the GST Portal will automatically suspend your GST registration. You can view the suspension order at: ➡️ Services → User Services → View Notices and Orders 🛠️ How to Fix This? To restore compliance, simply update your bank account through: ➡️ Registration → Amendment (Non-Core Fields) Once the details are added, the system will normally auto-drop the cancellation proceedings. If proceedings do not drop on the same day, you can manually close them using: ➡️ Initiate Drop Proceedings → Under View Notices & Orders ❗ Exemptions 📌 OIDAR and NRTP taxpayers are exempt. But if an OIDAR taxpayer has appointed an Indian representative, they must still provide bank account details. ✨ Stay compliant and update your bank details on time to avoid suspension!

🚨 Important GST Update for All Taxpayers! post imageRead full post

📢 GST Rule 14A – Do You Need to Reverse ITC?

Many businesses don’t realize this, but if you use goods or services for both taxable and exempt purposes, you may be required to reverse a portion of your Input Tax Credit (ITC) under Rule 14A of GST. 🔍 Who does Rule 14A apply to? It applies to GST-registered businesses that: ✔ Claim Input Tax Credit (ITC) ✔ Supply both taxable & exempt goods/services ✔ Use goods/services for mixed purposes (business + personal) 🛑 Not applicable to composition dealers (they cannot claim ITC). 📌 Simple Example: If you claim ITC on a purchase but use part of it for exempt or personal use → 👉 You must reverse the proportionate ITC as per Rule 14A. 💡 Why is this important? Ignoring ITC reversal may result in: ⚠ Tax demand ⚠ Interest ⚠ Penalty So it’s important to calculate it correctly. 📍 Need help calculating or filing Rule 14A reversal? We assist in GST compliance, ITC adjustment, and return filing. 📞 Delhi GST & Tax Experts 💬 Comment “GST HELP” to get guidance.

📢 GST Rule 14A – Do You Need to Reverse ITC? post imageRead full post

🚀 Fast GST Registration – Get GSTIN in Just 1 Day!

Starting a business? Don’t let paperwork slow you down! We help you get your GST Number quickly, accurately & hassle-free. ✨ Why Choose Us? ✔️ GST Number in 1 Day ✔️ Complete Documentation Support ✔️ Hassle-free Online Process ✔️ Budget-Friendly Service ✔️ Support for Business / Startup / Freelancer / Proprietorship 📍 Delhi GST & Tax Experts 📌 Required Documents: 🪪 PAN | Aadhaar | Address Proof | Photo | Bank Details 💬 Want to apply now? Comment “GST” or message us — we’ll guide you!

🚀 Fast GST Registration – Get GSTIN in Just 1 Day! post imageRead full post